What Is a Private Fund? Public vs Private Funds, Leverage, Liquidity Risk and Lessons From Redemption Suspensions
- Private funds raise money privately from a limited group and disclose less than public funds.
- Leverage, illiquid assets and weak information are their core risks.
- Korea's redemption suspensions show why suitability and clear explanation matter.
Contents
- How is a private fund different from a public fund?
- What types of private fund are there?
- What risks do private funds carry?
- What did Korea's redemption suspensions teach investors?
- How do the United States and the United Kingdom regulate private funds?
- How should you write up private funds in an assignment?
- FAQ
Most people picture a fund as something anyone can buy through a bank or an app. A private fund is different: it raises money privately from a limited group of investors, faces lighter rules, and discloses far less. This guide, adapted from a Korean finance study note, explains how private funds differ from public funds, the main types, why leverage and illiquidity make them risky, what Korea's fund redemption suspensions taught investors, and how the United States and the United Kingdom regulate the same products.
How is a private fund different from a public fund?
A public fund, such as a mutual fund or a listed exchange-traded fund, is offered to the general public. In return it must follow strict rules on what it can hold, how much it can borrow and what it must disclose. A private fund raises money without a public offering from a number of investors capped by law, and in exchange gets far more freedom over its assets and strategies.
Related on CampusDown Law UpI Think I Lost Money in a Crypto Investment Scam. What Now? — Lost money in a crypto investment scam?
That freedom comes with less information. Investors often cannot see exactly what the fund owns, and many private funds only let investors take money out at set intervals, or not at all until the fund winds up.
A note on terms: the Korean word usually translated as private equity fund covers every privately offered fund, including hedge-fund-style strategies and funds that lend money or buy property. In English, private equity normally means only funds that buy companies. This guide uses private fund for the broad Korean category.
What types of private fund are there?
Since a 2021 overhaul, Korea's Financial Investment Services and Capital Markets Act splits private funds into two groups: funds open only to institutional investors, and general private funds that can also take wealthy individuals who meet the qualifying conditions. The legal cap on investors in a single private fund was raised to 100 at the same time, with ordinary qualifying investors limited to a smaller number within that.
| Type | Typical strategy | Who can invest |
|---|---|---|
| Institutional-only fund | Buyouts: buy control of a company, improve it and sell it | Pension funds, insurers and other institutions |
| General private fund | Stocks, bonds, property, loans, hedge-fund strategies | Institutions and qualifying individuals with high minimum tickets |
| Public fund (for contrast) | Rules-based portfolios, including index funds and ETFs | Anyone |
Compared with an index fund that simply tracks a market, private funds use a much wider range of strategies, which also means a much wider range of outcomes.
Skimming the section headings first makes a long guide much easier to map out. Try writing down one question of your own as you read.
What risks do private funds carry?
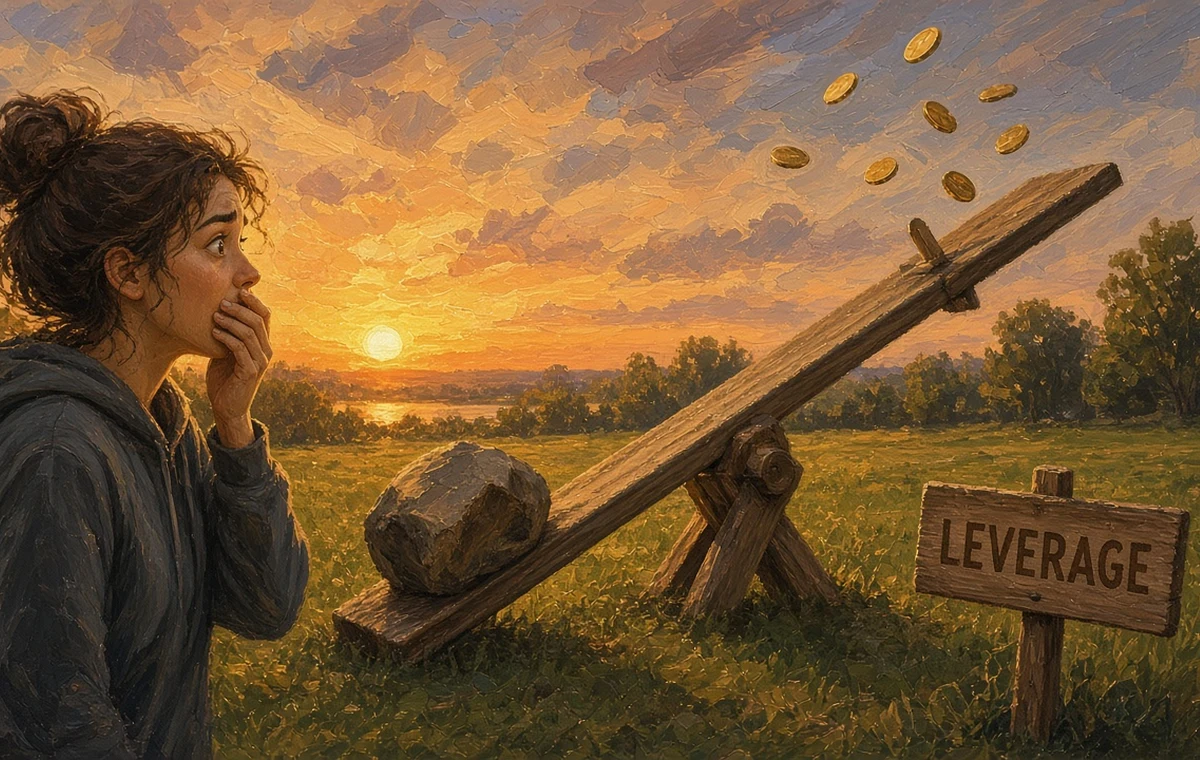
Many private funds borrow to increase the size of their bets. Borrowing raises returns when things go well and deepens losses when they do not. The idea is explained in the wiki entry on leverage.
| Risk | What happens | What to check |
|---|---|---|
| Leverage | Gains and losses grow together | How much the fund can borrow |
| Liquidity | Assets that are hard to sell cannot meet a rush of redemption requests | When and how you can redeem |
| Information | Managers can hide poor assets or move money between funds | Custodian checks and reporting |
| Mis-selling | High-risk products are sold as if they were safe | Whether the explanation matches the documents |
The most dangerous combination is a fund that promises easy access to cash while holding assets that are slow to sell, such as unlisted loans or property. When many investors ask for money back at once, the fund has to suspend redemptions. That is why the seller's duty to explain and the custodian's oversight matter so much.
What did Korea's redemption suspensions teach investors?
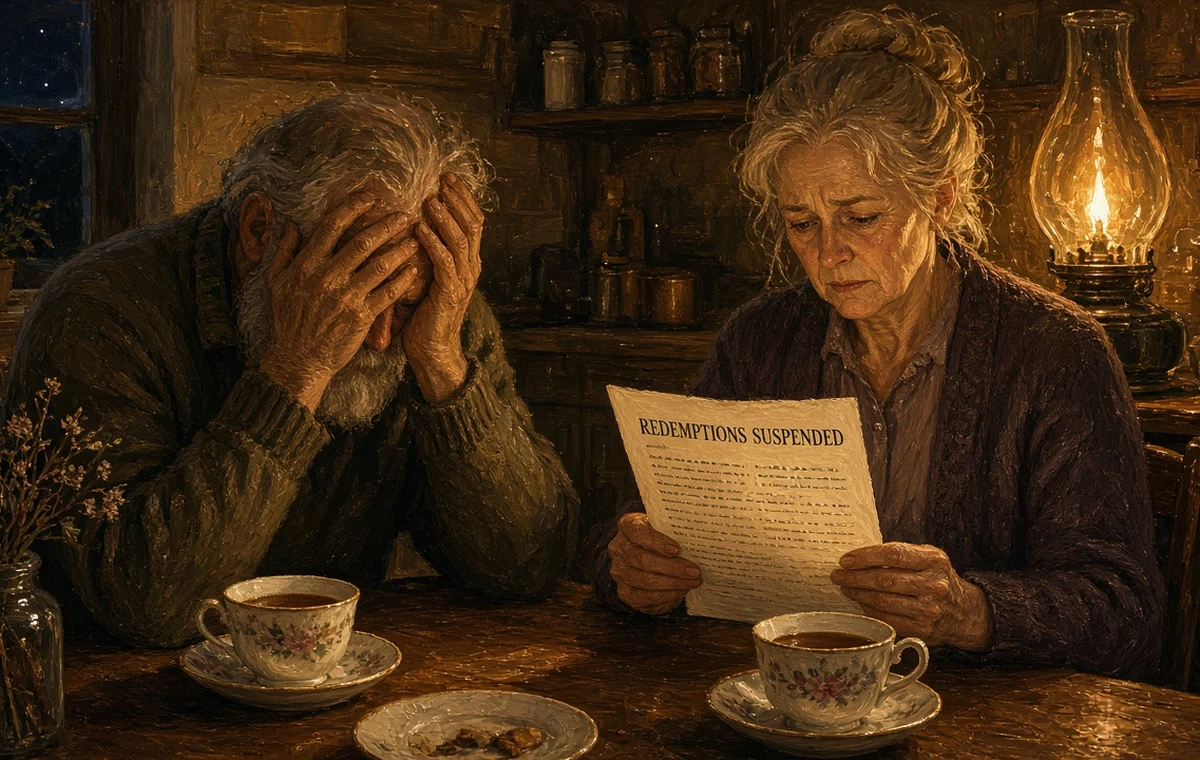
From 2019, several Korean private funds, including high-profile cases at Lime Asset Management and Optimus Asset Management, suspended redemptions on a large scale, and many individual investors suffered losses. Investigations pointed to mis-selling as a core problem: complex, illiquid products had been sold through banks and brokers as if they were low-risk.
The response was a stronger Financial Consumer Protection Act, in force from 2021, which tightened the duty to explain and the suitability principle, together with stricter supervision of how private funds are run and sold. The basic lesson is simple: if you cannot explain a product's risks, do not buy it.
Before investing, read the offering documents for the underlying assets, when you can redeem, the fee structure and the manager's track record. If a salesperson's explanation differs from the documents, keep a record of it, and if something is unclear, it is safer to wait.
How do the United States and the United Kingdom regulate private funds?
United States
American private funds usually rely on exemptions in the Investment Company Act of 1940, either by limiting the number of investors or by accepting only very wealthy qualified purchasers, and they sell under private placement rules to accredited investors who meet income or net worth tests. Larger advisers register with the Securities and Exchange Commission and file regular reports. The SEC adopted new private fund adviser rules in 2023, but a federal appeals court struck down major parts of them in 2024, so disclosure still depends heavily on what investors negotiate.
United Kingdom
In the United Kingdom the Financial Conduct Authority limits how high-risk and illiquid investments can be marketed to ordinary consumers, and many products can only be promoted to certified high net worth or sophisticated investors. The 2019 suspension of the Woodford Equity Income Fund, a public fund that held too many hard-to-sell shares, became the standard British example of a liquidity mismatch, and it pushed regulators to look harder at funds that promise daily dealing while holding illiquid assets.
| Item | United States | United Kingdom | Korea (source country) |
|---|---|---|---|
| Who can invest | Accredited investors and qualified purchasers | Certified high net worth or sophisticated investors | Institutions and qualifying individuals |
| Main regulator | SEC | FCA | Financial Services Commission and FSS |
| Landmark lesson | Debate over fee and performance disclosure | Liquidity mismatch after the Woodford suspension | Mis-selling behind redemption suspensions |
Putting the three side by side shows the same pattern: private funds are allowed precisely because their investors are assumed to understand and bear the risk, so problems start when products reach people who do not.
How should you write up private funds in an assignment?
For a financial products assignment, set a private fund next to a transparent product such as an exchange-traded fund and compare disclosure, liquidity and risk. The differences become clear in a single table, and the comparison shows why a regulator treats the two so differently.
Also on CampusDown Law Up: I Think I Lost Money in a Crypto Investment Scam. What Now?
In the conclusion, stress that understanding a product's structure comes before chasing its return. A choice is only well founded when the investor can explain the product in their own words. This guide is general study material, not investment advice.
- Private funds raise money privately from a limited number of investors and disclose less.
- The Korean term covers more than English private equity.
- Leverage, illiquidity and weak information are the core risks.
- Korea's redemption suspensions led to stronger consumer protection from 2021.
- The US and UK limit private funds to investors assumed to bear the risk.
FAQ
What is the difference between a public fund and a private fund?
A public fund is offered to anyone under strict rules and disclosure; a private fund raises money privately from a limited number of investors with more freedom and less disclosure.
Is a private fund the same as private equity?
Not exactly. In English private equity usually means funds that buy companies, while the Korean term for private funds also covers hedge-fund, loan and property strategies.
Why do private funds suspend redemptions?
When they hold assets that are slow to sell and many investors ask for money back at once, they cannot pay everyone in time.
What changed in Korea after the redemption suspensions?
The Financial Consumer Protection Act from 2021 tightened the duty to explain and the suitability principle, and supervision of private funds became stricter.
What should I check before investing in a private fund?
The underlying assets, when you can redeem, the fee structure, how much the fund can borrow and the manager's track record.